What does a fee do to a prediction market’s price?
research/lmsr-fees
Proportional fees on an LMSR verification market: exact no-trade band [q/(1+f),(q+f)/(1+f)], price lag q/(1+f), dead-market cliff f ≥ 2a−1 (threshold 2 atanh f at ½), exact fee revenue f·b·ln((1−p₀)/(1−p_T)), and a break-even fee that costs +38% Brier error.
What it found
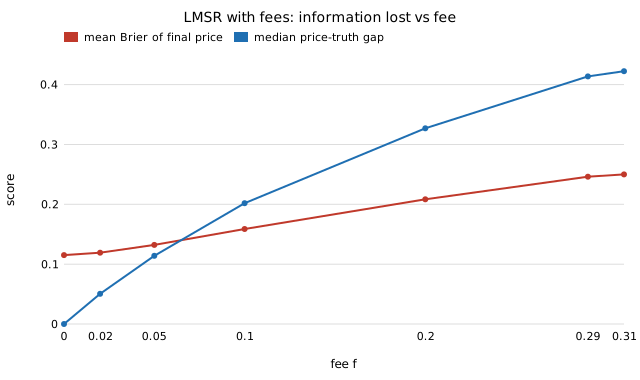
A proportional fee f on an LMSR verification market gives every trader an exact no-trade band [q/(1+f), (q+f)/(1+f)] of width f/(1+f), so an informed trader leaves the price at q/(1+f). At price ½ a signal of log-likelihood ratio λ moves the price iff f < tanh(λ/2) = 2a−1, above which the market is dead; fee revenue on a monotone path is exactly fb ln((1−p0)/(1−pT)). With ten 0.65-accurate traders, the break-even fee (≈0.11) raises Brier error from 0.115 to about 0.16 and revenue is hump-shaped in f. Naive traders, synthetic signals.
A figure from its own output
Paper, code and results
More in Prediction-market design
- What is a seat in a prediction market worth?Sequential LMSR seat rents are conditional mutual information: they telescope to the maker's expected loss (≤
b ln 2), fall with position at the Chernoff rate, order only redistributes a fixed total, and entry costs make error fall only ~1/bin the subsidy. - How fast does a prediction market converge when traders only understand part of it?Convergence of cost-function markets with partially informed traders as randomized subspace descent: maker loss telescopes to
½(e₀'Ae₀−e_T'Ae_T), closed-form slowdown from correlated securities (31→356 rounds at c=0.95, d=5), A-conjugate bundles restore1−1/dexactly, noisy-belief step size is an SGD step (running mean beats best constant step), LMSR simulation checks the local rates. - What does a constant-product pool concede to informed traders?Constant-product AMMs as cost-function prediction markets: worst-case loss
C0never attained, informed-trader profit exactlyC0(1−n·GM(π))(ratio to LMSR →ln n, crossover at n=e), polynomial price tails (p=0.999 costs 3.4× LMSR), exact regret identity, no forgiveness gain under regime switches. - What does not knowing the horizon cost a market maker?LMSR with time-varying liquidity as anytime Hedge:
b_t = c*√tcosts exactly√2over the horizon-aware bound, doubling is 1.70× worse, and self-tuning liquidity makes the subsidy equal the accumulated mixability gap (1.3 vs 102 on easy data). - The subsidy cost of privacy in prediction marketsDifferentially private LMSR via the binary-tree mechanism: path-wise loss bound, and the accuracy/subsidy cost of privacy.
- Who pays for the information in a manipulated market?Manipulating an LMSR verification market: manipulator loss
b·KL(q‖τ)equals the extra informed rent, and manipulation raises accuracy only in a liquidity band (thin: costs1−2q; deep: neutral).
All 9 Prediction-market design projects →
Other research topics
Proper scoring & elicitation28Effort & peer prediction9Verification games & slashing19Detection & tolerances14Markets as routers13Prediction-market design9Paying contributors8Decentralised training systems23Digital twins & sim-to-real164LLM chip design loops40Robot manufacturing loops53Ambient AI assistant46Self-replicating manufacturing34Simulation-first design64Engineered clothing45Task-specific AI accelerators40Algorithmic chip-design loops42Open-source purpose-built robots44The software-engineering loop43Adversarial human imitation41Open-source residential construction41Autonomous multi-angle capture34Sensing, imaging and 3D31Energy supply and dense energy storage39Robot societies among people31Agentic co-design of low-cost robots27Laundry-hanging robots25Machine learning on qualitative data23Robots on the building site27Civilizations & group psychology1History & human sciences1
Produced with AI assistance (Claude). Results are from the code in this repository and are simulated or stylised unless the abstract says otherwise; nothing here implies affiliation with or endorsement by any lab, researcher or company cited. MIT licensed.